Written by Amaury de Barros Conti, Partner | Vice President Investments
WHAT MOVED MARKET LAST WEEK
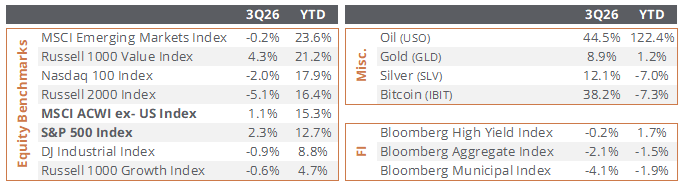
Markets absorbed the Federal Reserve’s first interest-rate increase since 2023 with relatively limited index-level disruption, but the week reinforced a more demanding investment environment. The Nasdaq Composite gained 0.7%, supported by renewed strength in technology and artificial intelligence-related companies. The S&P 500 was essentially unchanged, declining 0.1%, while the Dow Jones Industrial Average fell 1.7% for its third consecutive weekly decline. Mid-cap stocks declined 1.7%, and the Russell 2000 fell 1.5%, illustrating the greater sensitivity of smaller companies to higher borrowing costs, as per Bloomberg data.
- The Federal Open Market Committee unanimously raised the federal funds target range by 25 basis points to 3.75% to 4.00%. This was the Fed’s first increase since 2023. Updated projections indicated that 16 of 18 participants expected at least one additional increase in 2026. Chair Kevin Warsh characterized the move as a removal of accommodation, rather than the beginning of an aggressive tightening cycle, citing firmer economic growth, insufficient progress on inflation, and increased geopolitical uncertainty.
- Incoming economic data broadly supported the Fed’s assessment. August retail sales increased 1.2% from the prior month, initial jobless claims declined to 196,000, and industrial production was unchanged. Manufacturing surveys continued to indicate expansion, although both the New York and Philadelphia Fed reports pointed to firmer input costs. Taken together, the data indicated an economy with resilient consumer demand and labor-market conditions, but persistent cost pressures that may limit the Fed’s flexibility.
- Attacks on Saudi infrastructure and disruptions to regional transportation routes initially pushed Brent crude toward $110 per barrel. Oil prices subsequently retreated after reports indicated that pipeline damage may have been less severe than initially feared, with WTI crude ending near $100 per barrel.
- The Senate failed to advance the CLARITY Act, falling 11 votes short of the 60 needed, and the agencies moved anyway. The SEC announced a five-year conditional exemption under which approved venues may trade tokenized versions of US-listed stocks, provided the digital shares preserve dividend and voting rights and halt when the underlying exchange halts.
- Trade policy re-entered the frame. Canada confirmed that it is exploring an Association Agreement with the European Union amid strained relations with Washington, drawing renewed tariff threats against both Ottawa and Brussels.
LOOKING AHEAD
- The week may help clarify whether markets view the September rate increase as a limited policy adjustment or the beginning of a more sustained tightening phase. Investors will likely focus on speeches from Federal Reserve officials, flash purchasing managers’ indexes, initial jobless claims, new home sales, durable goods orders, and the final September consumer sentiment reading.
- Treasury auctions across the 2-, 5-, and 7-year maturities will provide an important test of demand at current yields. With the 10-year Treasury yield near 5% and corporate issuance also elevated, weak auction demand could place further upward pressure on term premiums.
- On the corporate calendar, Costco is expected to be the most closely watched earnings report, with additional updates from consumer, logistics, and business services companies.

Amaury de Barros Conti
Partner | Vice President Investments
Source: Bloomberg, TheStreet, Reuters, CNBC, Seeking Alpha, Benzinga, Yahoo Finance, Kiplinger, T. Rowe Price, RBC Global Asset Management, Gemmer Asset Management, Eurostat, Bank of England, Bank of Japan, U.S. Census Bureau, U.S. Department of Labor, Federal Reserve Banks of Atlanta, New York, and Philadelphia, Board of Governors of Federal Reserve System, U.S. Bureau of Labor Statistics, University of Michigan, and third-party market commentary supplied by the recipient. Data as of September 18, 2026, unless otherwise noted.
General Disclaimer: This material is provided for informational purposes only and should not be construed as investment, legal, or tax advice. Sendero Wealth Management LLC is an SEC-registered adviser; registration does not imply skill. References to specific securities are for informational purposes and do not constitute a recommendation to buy, sell, or hold any security. Views are as of the date noted, may change without notice, and forward-looking statements are not guarantees of future results. Data from third-party sources is believed to be reliable but is not guaranteed; indices are unmanaged and not available for direct investment. Past performance is not indicative of future results. All investments involve risk, including possible loss of principal. Consult your professional advisers regarding your specific circumstances. Review our Form ADV & Form CRS here.