Written by Amaury de Barros Conti, Partner | Vice President Investments
WHAT MOVED MARKETS LAST WEEK
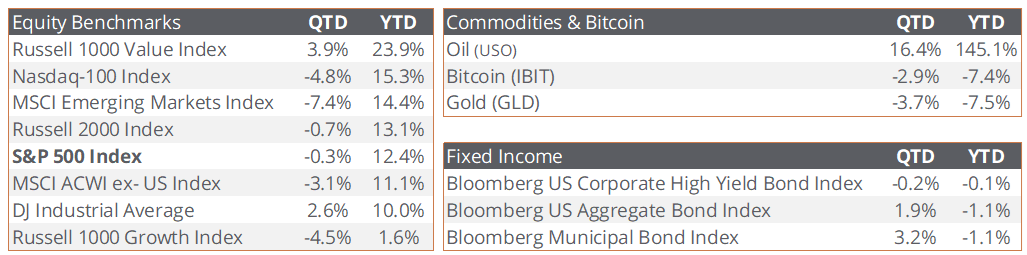
Markets delivered a mixed performance as investors balanced two competing narratives: continued economic resilience and growing concerns about the cost, financing, and ultimate return on the massive capital investments supporting artificial intelligence infrastructure. While large-cap technology stocks came under pressure, leadership broadened into value-oriented and smaller-cap stocks. The rotation beneath the surface of the market was notable. The Russell 2000 gained 2.0% and the Dow Jones Industrial Average rose 0.4%, while the S&P 500 declined 0.5% and the Nasdaq Composite fell 0.7%, as per Bloomberg data. This marked a third consecutive week in which value stocks outperformed growth stocks, suggesting investor leadership is becoming less concentrated than earlier in the year.
- Investor concerns intensified after Meta raised the low end of its 2026 capital expenditure outlook to $135-$145 billion from $130-$145 billion, reigniting questions about how long hyperscalers can sustain unprecedented investment levels and when those investments will generate meaningful returns.
- Treasury markets posted a strong rally as investors sought safety amid the technology selloff and heightened geopolitical uncertainty. The 10-year Treasury yield fell from 5.09% to 4.99%, briefly closing below 5% for the first time in nearly a month, while the 2-year Treasury yield declined from 4.74% to 4.65%. According to market commentary, Thursday’s move represented one of the strongest single-day Treasury rallies since March 2023.
- Consumer sentiment data showed one-year inflation expectations rising to 4.7%, while survey respondents continue to cite energy prices as a primary concern. The bond market’s performance suggests investors are increasingly focused on slowing growth-sensitive sectors such as housing, even as inflation pressures persist.
- Oil prices moved sharply higher late in the week after renewed tensions in the Middle East. For the week ended October 23, Brent crude rose 6% to $116.72 per barrel, its highest level since April, while WTI crude settled at $103.27, up 2.3%. Developments included reported Houthi attacks in Saudi Arabia, disruptions near critical Gulf energy infrastructure, and a U.S. authorization for an emergency Strategic Petroleum Reserve exchange.
- In our view, the most notable weakness in the U.S. economy continues to be housing. Builder confidence fell to 29, its lowest reading since 2012, while pending home sales declined 7.3% and reached the lowest level since the series began in 2001. Elevated mortgage rates, labor shortages, and rising construction costs continue to pressure activity.
LOOKING AHEAD
- The week could be one of the most important of the quarter. The Federal Reserve is widely expected to leave rates unchanged at its October 28 meeting, but investors will focus on Chair Kevin Warsh’s comments regarding inflation, energy prices, and the likelihood of additional rate increases in December or early 2027. Fed funds futures imply only a limited chance of an immediate hike, but markets continue to price additional tightening over the next several quarters.
- Investors will also receive several key economic reports, including third-quarter GDP, September PCE inflation, consumer confidence, and the Employment Cost Index. Meanwhile, earnings reports from Microsoft, Alphabet, Amazon, and other technology leaders will provide important insight into AI spending trends, cloud demand, and whether investors remain willing to support elevated capital expenditure plans.

Amaury de Barros Conti
Partner | Vice President Investments
Source: Index returns and oil prices, Bloomberg, for the period from October 1 (QTD) or January 1 (YTD) through October 23, 2026. Treasury yields, U.S. Treasury; consumer sentiment, University of Michigan; builder confidence, NAHB/Wells Fargo Housing Market Index; pending home sales, National Association of Realtors; fed funds futures, CME FedWatch; Meta capital expenditure outlook, Meta Platforms earnings release. All as of October 23, 2026 unless noted. Commodities & Crypto returns are represented by ETFs (ticker provided above), used as proxies where the exposure is not directly investable index returns are not available. ETF returns reflect total price return with distributions reinvested and are net of each fund’s operating expenses; the index returns shown elsewhere on this page are gross of fees, so the two are not directly comparable.
General Disclaimer: This material is provided for informational purposes only and should not be construed as investment, legal, or tax advice. Sendero Wealth Management, LLC is an SEC-registered adviser; registration does not imply skill. References to specific securities are for informational purposes and do not constitute a recommendation to buy, sell, or hold any security. Views are as of the date noted, may change without notice, and forward-looking statements are not guarantees of future results. Data from third-party sources is believed to be reliable but is not guaranteed; indices are unmanaged and not available for direct investment. Past performance is not indicative of future results. All investments involve risk, including possible loss of principal. Consult your professional advisers regarding your specific circumstances. Review our Form ADV & Form CRS here.