Written by Amaury de Barros Conti, Partner | Vice President Investments
WHAT MOVED MARKETS LAST WEEK
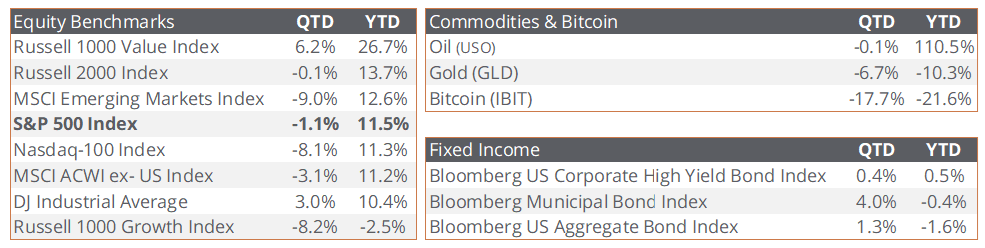
U.S. equities rebounded after four consecutive weekly declines, but the recovery was accompanied by a meaningful rise in Treasury yields and renewed volatility in semiconductor shares. Hotter consumer inflation, elevated producer prices, and still-low unemployment claims strengthened the case for another Federal Reserve rate increase in December. At the same time, lower oil prices and broader participation outside the largest technology companies helped offset some of the pressure from tighter financial conditions. The S&P 500 gained 2.5%, the Dow Jones Industrial Average rose 2.1%, and the Nasdaq Composite advanced 2.3%, as per Bloomberg data.
- Nvidia shares fell approximately 12.8% for the week following an abrupt leadership transition, with Chief Financial Officer Colette Kress appointed interim chief executive while the board conducts a search.
- The 10-year Treasury yield ended near 5.15%, roughly 29 basis points above the prior Friday, while the two-year yield finished near 4.87%, up approximately 34 basis points. Futures markets ended the week assigning roughly a 90% probability to a 25-basis-point increase at the Federal Reserve’s December 8-9 meeting, although market-implied probabilities can change quickly as new data arrives.
- October CPI increased 0.4% month over month, above the 0.3% consensus estimate, while core CPI rose 0.3% for a third consecutive month. The three-month annualized core rate accelerated to approximately 3.7%, its fastest pace in more than two years. Food prices increased 0.5% and energy prices rose 0.7%. Final-demand PPI rose 0.3% in October and 6.5% from a year earlier, the largest annual increase since November 2022. The narrower core measure excluding food, energy, and trade services increased 0.5% for the month and 4.9% year over year. Meanwhile, initial unemployment claims totaled 200,000 and have remained at or below that threshold since mid-September. We believe the combination of persistent inflation and limited labor-market deterioration leaves policymakers with room to maintain a restrictive stance.
LOOKING AHEAD
- Federal Reserve communication and consumer data will shape the rate outlook. Chair Kevin Warsh and New York Fed President John Williams are scheduled to speak Monday, November 16, and minutes from the October 27-28 FOMC meeting are scheduled for release on Wednesday, November 18. October retail sales, housing starts, weekly jobless claims, and final November consumer sentiment will help investors assess whether demand is slowing enough to reduce inflation without materially weakening employment.
- Anthropic’s initial public offering is expected to price on November 18, with shares expected to begin trading on Thursday, November 19. Separately, Nvidia earnings will test confidence in the AI capital-spending cycle. The company is scheduled to report after Tuesday’s close. Beyond revenue and earnings, investors will focus on the leadership search as well as customer demand. Results from Home Depot, Target, and Walmart will provide a complementary view of household demand and margin pressure.
- Congress has returned for a lame-duck session, and federal funding expires December 11. Negotiations involving energy permitting, transmission investment, and the allocation of data-center power and grid costs could affect utilities, infrastructure, and technology capital spending.

Amaury de Barros Conti
Partner | Vice President Investments
Source: Index returns and Nvidia share-price change: Bloomberg; Treasury yields, FOMC meeting dates, minutes schedule, and speaker schedule: Federal Reserve Board, Federal Reserve Bank of New York; December rate-increase probability: CME FedWatch; consumer and producer price data: U.S. Bureau of Labor Statistics, October 2026 CPI and PPI releases; three-month annualized core CPI calculated from BLS data; CPI consensus estimate: Reuters; initial unemployment claims: U.S. Department of Labor; Nvidia leadership transition: Nvidia Form 8-K filed November 12, 2026; earnings dates for Nvidia, Home Depot, Target, and Walmart: company investor-relations materials; Anthropic offering timing and federal funding deadline: Reuters / CNBC / Axios]. Data is as of November 13, 2026 unless otherwise stated. Commodities & Crypto returns are represented by ETFs (ticker provided above), used as proxies where the exposure is not directly investable index returns are not available. ETF returns reflect total price return with distributions reinvested and are net of each fund’s operating expenses; the index returns shown elsewhere on this page are gross of fees, so the two are not directly comparable. Market-implied probabilities and consensus estimates can change. QTD reflects returns from October 1 through November 13, 2026, and YTD reflects January 1 through November 13, 2026.
General Disclaimer: This material is provided for informational purposes only and should not be construed as investment, legal, or tax advice. Sendero Wealth Management LLC is an SEC-registered adviser; registration does not imply skill. References to specific securities are for informational purposes and do not constitute a recommendation to buy, sell, or hold any security. Views are as of the date noted, may change without notice, and forward-looking statements are not guarantees of future results. Data from third-party sources is believed to be reliable but is not guaranteed; indices are unmanaged and not available for direct investment. Past performance is not indicative of future results. All investments involve risk, including possible loss of principal. Consult your professional advisers regarding your specific circumstances. Review our Form ADV & Form CRS here.