Written by Amaury de Barros Conti, Partner | Vice President Investments
WHAT MOVED MARKET LAST WEEK
U.S. equities finished higher despite another volatile week in rates, energy, and technology. The S&P 500 gained 1.2%, the Dow Jones Industrial Average rose 0.9%, and the Nasdaq Composite advanced 0.6%, marking its fourth consecutive weekly gain, as per Bloomberg data. The S&P 500 also reached a record during the week.
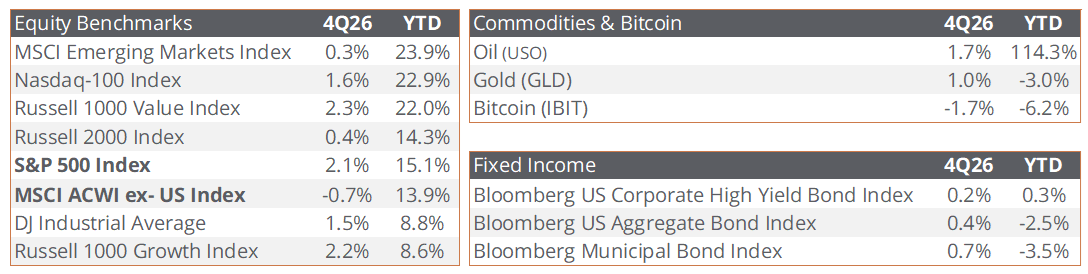
- Technology experienced notable volatility as investors increasingly scrutinized the relationship between artificial intelligence investment and future profitability. AI infrastructure stocks sold off Thursday amid questions about OpenAI’s revenue trajectory, although technology recovered on Friday. Separately, SpaceX announced an approximately $8 billion transaction to acquire a nationwide low-band spectrum license portfolio, which disrupted telecommunications stocks and illustrated how technological change can rapidly alter competitive expectations within established industries.
- Treasury yields again reached multi-decade highs before retreating later in the week. The 30-year Treasury yield rose to approximately 5.73%, while the 10-year reached roughly 5.36%. Stronger-than-expected Treasury auction demand helped stabilize the market, allowing the 10-year to finish the week near 5.24%, approximately four basis points below the previous Friday. The 2-year yield ended near 4.80%. Meanwhile, thirty-year mortgage rates increased to 7.49%, their highest level since November 2023.
- Consumer data were less constructive. Preliminary October consumer sentiment declined to 46.3 from 48.1 in September, a five-month low, while year-ahead inflation expectations increased to 4.7%. The New York Fed’s Survey of Consumer Expectations provided a similar signal, with one-year inflation expectations increasing to 3.9%, their highest level since May 2023.
LOOKING AHEAD
- The coming week brings two important tests for markets: September inflation data and the beginning of third-quarter earnings season.
- September CPI is scheduled for Wednesday. Consensus estimates call for a 0.6% monthly increase and 3.6% year-over-year headline inflation, while core CPI is expected to rise 0.2% for the month and 2.5% from a year earlier. The report will be particularly important following the recent rise in Treasury yields and ahead of the Fed’s October 27-28 meeting.
- Third-quarter earnings also begin in earnest, with JPMorgan, Goldman Sachs, Wells Fargo, and Citigroup scheduled to report Tuesday, followed by Bank of America, Morgan Stanley, and BlackRock on Wednesday. Taiwan Semiconductor reports Thursday and should provide an important read on semiconductor and AI-related demand. For financial companies, investors are likely to focus on credit quality, capital-markets activity, consumer health, and the impact of higher borrowing costs.

Amaury de Barros Conti
Partner | Vice President Investments
Source: Source: Bloomberg, Seeking Alpha, TheStreet, Reuters, CNBC, Benzinga, Kiplinger, Barclays, Bloomberg Economics, Bloomberg Intelligence, third-party strategy research and published commentary supplied by the recipient, Census Bureau, Department of Labor, BEA, S&P Global, Cleveland, Richmond and Kansas City Feds, University of Michigan, CME FedWatch. Data as of October 2, 2026.
General Disclaimer: This material is provided for informational purposes only and should not be construed as investment, legal, or tax advice. Sendero Wealth Management LLC is an SEC-registered adviser; registration does not imply skill. References to specific securities are for informational purposes and do not constitute a recommendation to buy, sell, or hold any security. Views are as of the date noted, may change without notice, and forward-looking statements are not guarantees of future results. Data from third-party sources is believed to be reliable but is not guaranteed; indices are unmanaged and not available for direct investment. Past performance is not indicative of future results. All investments involve risk, including possible loss of principal. Consult your professional advisers regarding your specific circumstances. Review our Form ADV & Form CRS here.