Written by Amaury de Barros Conti, Partner | Vice President Investments
WHAT MOVED MARKET LAST WEEK
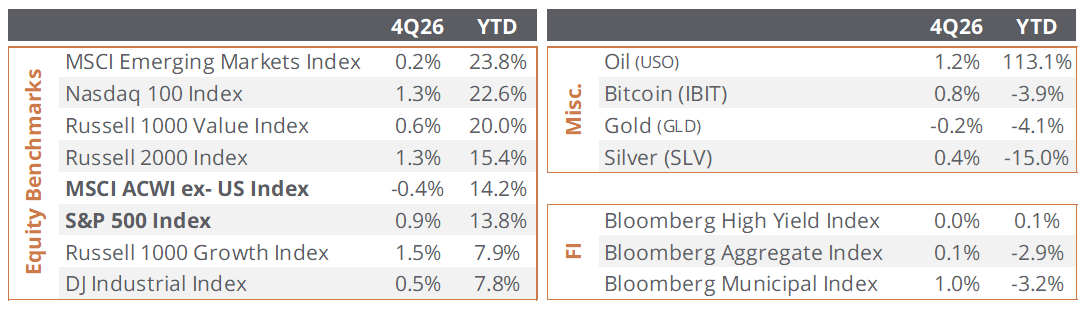
Markets experienced several developments that would ordinarily support lower interest rates: inflation data were revised downward, September payroll growth slowed considerably, and Federal Reserve commentary that was generally interpreted as suggesting less urgency to tighten policy. Yet longer-term Treasury yields moved in the opposite direction, underscoring that bond markets are responding to factors beyond expectations for Federal Reserve policy alone. U.S. equities were mixed for the week. The Nasdaq Composite gained 0.5% while the S&P 500 declined 0.3%, and the Dow Jones Industrial Average fell 1.3%, as per Bloomberg data.
- A key development was the September employment report. Nonfarm payrolls increased by just 29,000, well below consensus estimates of roughly 84,000 to 90,000. Both July and August employment were revised lower as the unemployment rate increased to 4.2%.
- Headline PCE inflation increased 0.3% in August and 3.4% from a year earlier, while core PCE rose 0.2% for the month and 3.0% year over year. Annual benchmark revisions lowered previously reported inflation rates.
- On the other hand, consumer confidence fell to 81.9, its lowest level since 2014, while consumers’ average 12-month inflation expectations increased to 6.1%.
- Brent crude initially traded above $108 per barrel before declining after the G7 and its partners agreed to release up to 100 million barrels of emergency crude and diesel inventories over four months.
LOOKING AHEAD
- The October 7 release of minutes from the Federal Reserve’s September meeting will be closely watched, although investors should recognize that the meeting occurred before the latest PCE revisions and September employment report. The next FOMC policy decision is scheduled for October 28.
- The economic calendar includes ISM Services, the August trade balance, jobless claims, consumer credit, and preliminary University of Michigan consumer sentiment. Treasury supply will be equally important, with auctions of 3-, 10-, and 30-year securities scheduled during the week. With long-term yields already at multi-decade highs, investor demand for the 10- and 30-year auctions may provide an important indication of whether recent yield pressure is beginning to attract longer-term buyers.
- Attention will soon turn to third-quarter earnings. The source material cites consensus expectations for approximately 27% year-over-year S&P 500 earnings growth, with artificial intelligence infrastructure beneficiaries contributing significantly to index-level growth. Importantly, expected earnings growth for the median S&P 500 company is considerably lower at approximately 9%, highlighting the continued concentration of earnings momentum within the index.

Amaury de Barros Conti
Partner | Vice President Investments
Source: Source: Bloomberg, Seeking Alpha, TheStreet, Reuters, CNBC, Benzinga, Kiplinger, Barclays, Bloomberg Economics, Bloomberg Intelligence, third-party strategy research and published commentary supplied by the recipient, Census Bureau, Department of Labor, BEA, S&P Global, Cleveland, Richmond and Kansas City Feds, University of Michigan, CME FedWatch. Data as of October 2, 2026.
General Disclaimer: This material is provided for informational purposes only and should not be construed as investment, legal, or tax advice. Sendero Wealth Management LLC is an SEC-registered adviser; registration does not imply skill. References to specific securities are for informational purposes and do not constitute a recommendation to buy, sell, or hold any security. Views are as of the date noted, may change without notice, and forward-looking statements are not guarantees of future results. Data from third-party sources is believed to be reliable but is not guaranteed; indices are unmanaged and not available for direct investment. Past performance is not indicative of future results. All investments involve risk, including possible loss of principal. Consult your professional advisers regarding your specific circumstances. Review our Form ADV & Form CRS here.