Written by Amaury de Barros Conti, Partner | Vice President Investments
WHAT MOVED MARKET LAST WEEK
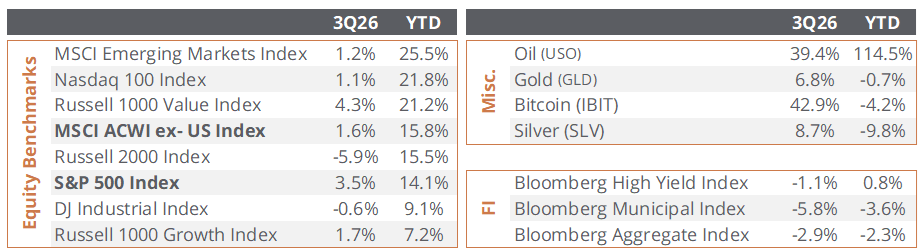
Financial markets navigated an unusual combination: long-term interest rates reached multi-decade highs, yet major U.S. equity indexes advanced. The 10-year Treasury yield briefly touched 5.23%, its highest level since 2007, while the 30-year yield reached 5.50%, its highest level since 2004. The Nasdaq Composite led the major indexes with a weekly gain of 2.06%, while the S&P 500 gained 1.21%, and the Dow Jones Industrial Average gained 0.28%, while the. The Russell 2000 declined 0.80%, reflecting the greater sensitivity of smaller companies to financing costs, as per Bloomberg data.
- The increase in long-term yields reflects a combination of resilient economic growth, heavy Treasury issuance, substantial corporate borrowing associated with artificial intelligence infrastructure, and expectations that the Federal Reserve may raise rates further.
- September business surveys pointed to a strong pace of private-sector activity. The S&P Global manufacturing purchasing managers’ index increased to 57.0 from 53.9 in August, its strongest reading since May 2022, while the services index rose to 58.7 from 56,5 in August.
- Labor and housing data provided additional evidence of resilience. Initial unemployment claims totaled 197,000 for the week ended September 19, remaining near historically low levels. August new home sales increased 6.4% to an annualized rate of 684,000, exceeding expectations, although the median sales price declined 5.8% from the prior year.
- Consumer sentiment presented a less encouraging picture. The University of Michigan’s final September sentiment reading was revised modestly higher to 48.1 but remained near historic lows. Year-ahead inflation expectations increased from 4.0% to 4.6%, while longer-term expectations held at 3.4%.
- U.S.-China discussions produced a two-month extension of the existing trade truce through January 10, 2027, and announced reciprocal tariff reductions covering a limited group of goods; however, there was no structural resolution of the countries’ principal technology and trade disputes. The conciliatory tone may reduce near-term tensions, but the relationship remains defined by strategic competition and unresolved policy differences.
LOOKING AHEAD
- The upcoming employment report and personal consumption expenditures inflation release will be principal tests of the Federal Reserve’s policy outlook. Published payroll estimates vary considerably, reflecting uncertainty about whether recent labor-market strength can be sustained. Markets will also evaluate other releases scheduled for the week, including job openings, consumer confidence, manufacturing activity, jobless claims, construction spending, and factory orders.
- Corporate attention will center on Micron as an indicator of memory demand associated with artificial intelligence investment, while Nike’s results may provide insight into consumer demand and the progress of its business turnaround. Additional reports are expected from Accenture, McCormick, Acuity, Carnival, Conagra, and CarMax; reporting dates remain tentative unless confirmed by the companies.
- Key developments to monitor include three interrelated risks: whether economic strength prompts additional Federal Reserve tightening, whether long-term interest-rate volatility affects corporate credit, and whether geopolitical developments interrupt the recent improvement in physical energy flows.On the corporate calendar, Costco is expected to be the most closely watched earnings report, with additional updates from consumer, logistics, and business services companies.

Amaury de Barros Conti
Partner | Vice President Investments
Source: Bloomberg, Seeking Alpha, TheStreet, Reuters, CNBC, Benzinga, Kiplinger, Barclays, Bloomberg Economics, Bloomberg Intelligence, third-party strategy research and published commentary supplied by the recipient, Census Bureau, Department of Labor, BEA, S&P Global, Cleveland, Richmond and Kansas City Feds, University of Michigan, CME FedWatch. Data as of September 25, 2026.
General Disclaimer: This material is provided for informational purposes only and should not be construed as investment, legal, or tax advice. Sendero Wealth Management LLC is an SEC-registered investment adviser; registration does not imply skill. References to specific securities are for informational purposes and do not constitute a recommendation to buy, sell, or hold any security. Views are as of the date noted, may change without notice, and forward-looking statements are not guarantees of future results. Data from third-party sources is believed to be reliable but is not guaranteed; indices are unmanaged and not available for direct investment. Past performance is not indicative of future results. All investments involve risk, including possible loss of principal. Consult your professional advisers regarding your specific circumstances. Review our Form ADV & Form CRS here.